Recent weeks have marked a notable shift in how investors view President Trump's two principal economic officials: Treasury Secretary Scott Bessent and Federal Reserve Chair Kevin Warsh. The divergence stems from their distinct policy approaches and their relationships with the president, with Warsh gaining ground as an inflation hawk while Bessent's bond market maneuvers draw scrutiny.
Warsh's Credibility Builds
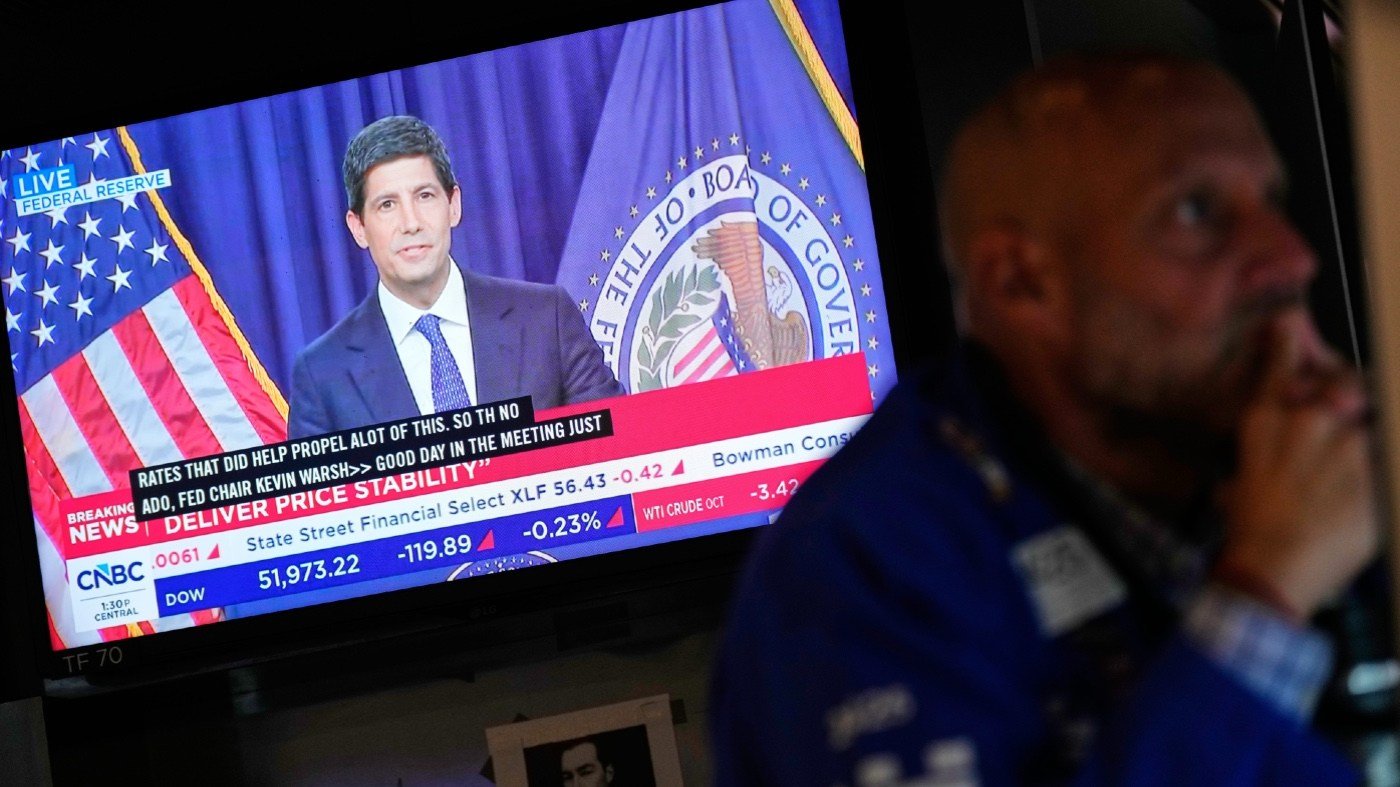
Warsh, who had a rocky start, has solidified his reputation as a committed inflation fighter. In his Jackson Hole address, he laid out a framework for achieving the Fed's dual mandate of maximum employment and price stability. His rhetoric was backed by action: the Federal Reserve raised its benchmark rate by a quarter point at the September FOMC meeting. Warsh made clear that controlling inflation was the Fed's paramount objective, and bond traders responded by pricing in a higher path for future rate increases.
Bessent's Bond Market Gambit Backfires
Bessent, in contrast, has faced criticism for his attempts to influence Treasury yields. He first intervened to support the yen, aiming to prevent Japanese authorities from selling U.S. debt. Then, in mid-August, he announced an expansion of long-dated Treasury buybacks. Yet yields have since soared to two-decade highs, and the market suffered its worst single-day selloff since Trump's "Liberation Day" tariffs. Investor Stanley Druckenmiller, who once mentored Bessent, publicly rebuked the buyback plan, arguing the government cannot buy its way out of structural deficits and warning that fighting market fundamentals undermines Treasury credibility. Bessent countered that his role is to ensure markets focus on fundamentals, not dictate policy.
Policy Philosophy Differences
While both Warsh and Bessent favor growth-oriented, pro-market policies and are skeptical of the Fed's massive bond purchases after the 2008 crisis, they differ sharply on bond yields. Warsh advocates for market-driven price discovery, while Bessent seeks to mitigate rising debt service costs. Mickey Levy of the Hoover Institution notes that Warsh's Jackson Hole speech signaled a new Fed framework, questioning the reliability of wage growth as an inflation indicator and commissioning five task forces to modernize monetary policy. Bessent, however, has not articulated a clear deficit-reduction strategy. He initially set goals of a 3% deficit-to-GDP ratio, 3% real growth, and a 3 million barrel daily oil production increase, but the deficit remains near 6% of GDP, and he has only suggested faster growth as the solution.
Trade and Trump Relations
Bessent earned praise for his handling of trade negotiations, particularly in averting a full-blown trade war with China last year by swiftly negotiating a truce. He has also been a key figure in other disputes, though his recent role in the U.S.-Canada impasse drew criticism. His trade diplomacy has been a bright spot.
Their interactions with Trump also set them apart. Warsh has managed Trump's expectations effectively, securing a unanimous rate hike vote without provoking presidential backlash, partly by consulting Trump beforehand. Bessent, meanwhile, has tended to acquiesce to Trump on tariffs and budget issues, avoiding confrontation. In a Financial Times column, Edward Luce described Bessent's behavior as "turning noticeably adolescent" and erratic, suggesting he is trying to please one man. Bessent has backed Warsh on the rate hike, but his overall approach raises concerns.
My initial hope was that Bessent would leverage his trade success to gain Trump's confidence and offer candid counsel. Now, I worry that if he continues to act as a cheerleader rather than a trusted advisor, his standing as Treasury secretary may erode further.
Nicholas Sargen, Ph.D., is an economic consultant affiliated with the Darden Business School and author of three books, including "Investing in the Trump Era."