New data from MoneyLion, shared with Nexstar, reveals that residents in some of the nation's most affordable states have experienced a dramatic doubling of their average debt over the past decade. The analysis, which spans 2015 to 2025, tracks both secured debts like mortgages and unsecured obligations such as credit card balances, along with auto and student loans.
Idaho leads the list with a 106% increase in total debt, followed closely by Utah at 104%. These states, along with Texas, have become magnets for new residents since the pandemic, driving up demand for housing and automobiles. The surge in mortgage debt in these states reflects their growing populations and the expectation that real estate values will continue to climb.

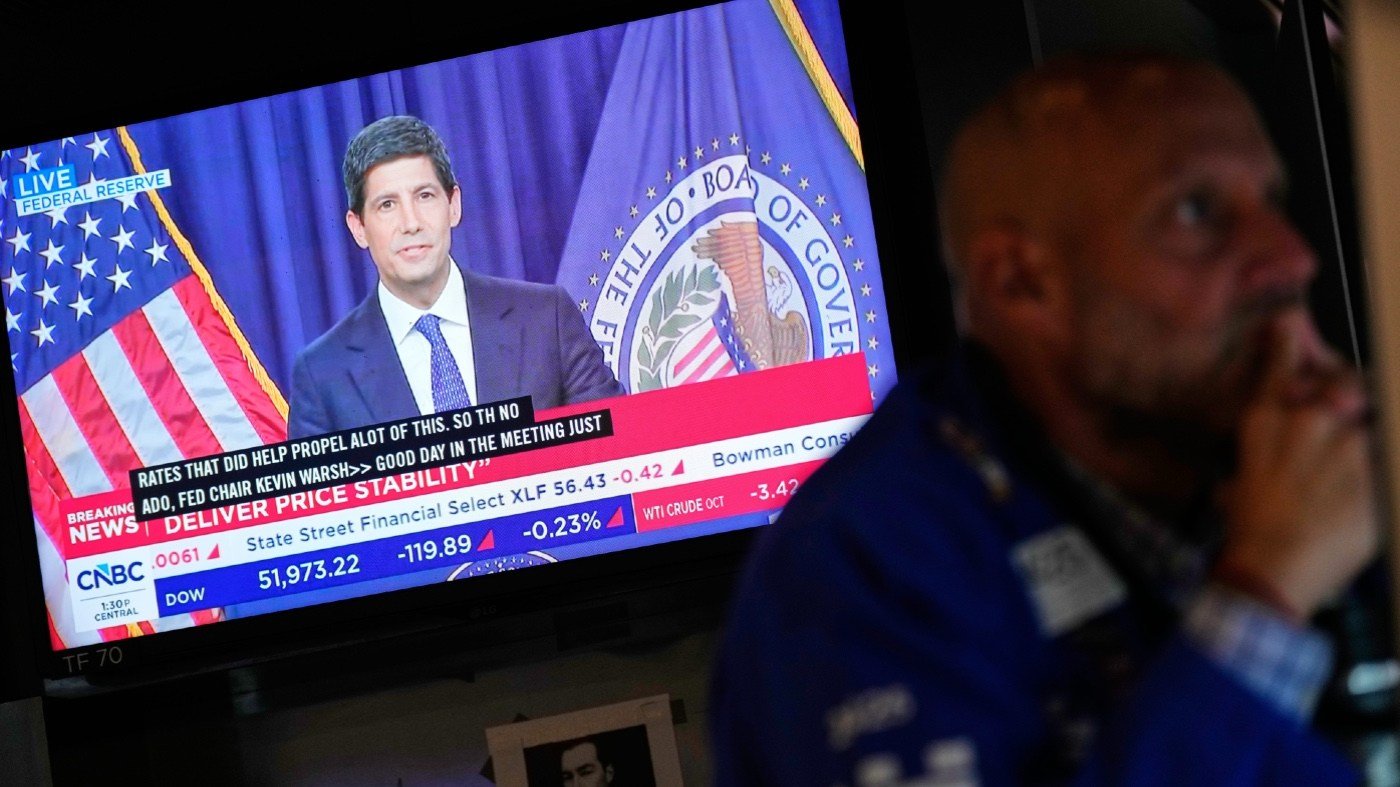
Credit card debt, which carries some of the highest interest rates, saw its steepest rise in Nevada. The state's collective credit card balances ballooned from $6 billion in 2015 to over $14 billion in 2025, an increase of more than 130%. This trend is particularly concerning given the recent move by the Federal Reserve to raise its benchmark interest rate by a quarter-point, the first such hike since mid-2023.
The Fed's decision, which lifts the target range to 3.75%–4.00%, will make borrowing more expensive for consumers. Those with existing credit card balances will see their monthly interest charges rise, and anyone planning to finance a major purchase—such as a home, car, or large appliance—will face higher costs. The rate hike is part of the central bank's effort to curb inflation, but it adds a new layer of financial strain for households already grappling with elevated debt levels.
Despite these pressures, the overall household debt service ratio—the share of after-tax income used for debt payments—remains relatively low by historical standards. This suggests that many families may not immediately feel the pinch, but the cumulative effect of rising rates and persistent debt could become more pronounced over time.
The states with the most significant debt growth over the past decade are concentrated in the South and West, regions that have seen robust population inflows. Beyond Idaho and Utah, Texas saw a 93% increase, Nevada 91%, Florida 88%, South Carolina 82%, Arizona 81%, Tennessee 77%, Colorado 75%, and North Carolina 72%. These figures highlight a broader trend: as people move to more affordable areas, they often take on larger mortgages and other debts, which can erode the financial advantages of lower living costs.
For policymakers, this data underscores the need to monitor regional debt dynamics, especially as the Fed tightens monetary policy. The recent rate hike could exacerbate financial stress in states where debt has already grown rapidly. Meanwhile, savers may benefit from higher interest rates on deposits, offering a silver lining for those who have built up cash reserves.
As the economic landscape shifts, residents in these high-growth states will need to navigate the delicate balance between opportunity and financial risk. The full impact of the Fed's rate increase will unfold in the coming months, but the warning signs are already visible in the debt statistics.